Find a Lawyer
Book an appointment with us, or search the directory to find the right lawyer for you directly through the app.
Find out more

Al Adalla
Read MoreA complete spectrum of legal services across jurisdictions in the Middle East & North Africa.


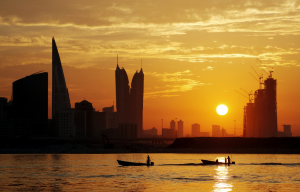
Regulation, Capital and Connectivity: Bahrain’s Competitive Edge in the Gulf
 12 min 18 sec
Written by

 s.qudah@tamimi.com
 View LinkedIn Profile

Against a shifting geopolitical landscape and evolving market dynamics, Bahrain continues to chart a steady course—demonstrating resilience and strategic clarity at a time when cross‑border capital flows and policy confidence are under pressure. Stability, continuity and long-term positioning have moved to the top of investor and boardroom agendas.
Bahrain’s competitive strength lies not in scale, but in the sophistication of its regulatory framework and its proactive approach to attracting and managing capital. In recent years, the Kingdom has decisively reshaped its corporate and investment ecosystem—delivering record FDI inflows, modernising its companies law to provide more flexible structures and greater investor control, and reinforcing its position as a cost‑efficient, innovation‑friendly hub.
For boards evaluating GCC exposure, Bahrain stands out as a focused, rules‑driven jurisdiction with depth across financial services, manufacturing, logistics, retail, tourism, ICT and shared‑services operations. Despite global headwinds, the Kingdom has maintained positive momentum—recording consistent FDI inflows through 2023–2026 and translating policy reform into tangible business confidence. This article explores the key pillars shaping that trajectory.
1. Economic and FDI Anchor: Finance, Manufacturing and Saudi Access
Bahrain remains one of the region’s most established and diversified financial centres. The financial and insurance sector consistently contributes around 17–18% of real GDP, making it the largest non-oil contributor to the economy. Manufacturing is another key pillar, accounting for a high-teens share of GDP, with aluminium and petrochemicals at its core. According to recent IMF and World Bank assessments, Bahrain’s real GDP grew by over 3% in 2024, supported by non-oil sector growth of around 3.8%. Growth is expected to remain in the range of just under 3% to the low-3% area through 2025–2026 as reforms and major projects continue to feed through. Non-oil sectors now account for roughly 85% of total output and are projected to edge higher over the medium term, led by financial services, manufacturing, logistics, tourism and the digital economy.
Foreign direct investment performance has outpaced global trends. In 2023, Bahrain attracted a record USD 6.8 billion in FDI inflows—a 148% increase from USD 2.8 billion in 2022—at a time when global FDI volumes declined. Inward FDI stock rose from USD 36.2 billion in 2022 to USD 43.1 billion in 2023 and to around USD 45.9 billion in 2024 (up approximately 5.7% year-on-year), giving Bahrain an FDI-stock-to-GDP ratio of close to 100% at end-2023—more than double the global average of about 47%. The Bahrain Economic Development Board reported BHD 680 million (approximately USD 1.8 billion) of direct investments in 2024, with the industrial sector receiving the largest share, followed by information technology, tourism and financial services. The Golden Licence programme for strategic projects, launched in April 2023, has also gained traction. Subsequent rounds announced in late 2024 and 2025 have lifted the cumulative portfolio to more than USD 6 billion, with recent beneficiaries including Bahrain Titanium, the National Bank of Kuwait’s first greenfield regional headquarters outside Kuwait, and a hyperscale data-centre facility by Beyon.
Most inward FDI stock comes from neighbouring GCC jurisdictions—Kuwait (36%), Saudi Arabia (23%) and the UAE (10%)—underscoring Bahrain’s role as a regional capital hub. The King Fahd Causeway provides direct overland access to Saudi Arabia, and many corporates continue to use Bahrain as a cost-efficient base for serving the Saudi market, particularly the Eastern Province. Financial and insurance services accounted for 64.2% of FDI inflows in Q1 2025, with manufacturing ranking second at 13.4%.
2. Corporate Framework: New Company Forms, Governance and Liability
Bahrain’s Commercial Companies Law (CCL) has been progressively reworked to make the jurisdiction more investor-ready. The most significant recent step is Decree-Law No. 38 of 2025, amending the CCL (Decree-Law No. 21 of 2001), which came into effect on 12 September 2025. The amendments represent a comprehensive reform package designed to align Bahrain’s corporate framework with international best practices, simplify processes and enhance transparency. Key changes include:
- Expanded personal liability for directors and shadow managers: Article 18 bis expressly extends personal and joint liability to directors, board members and any person acting as a de facto or shadow manager where negligence, gross error or a breach of law or the company’s constitutional documents causes loss to the company, its shareholders or third parties. Founders, partners and capital owners are no longer personally liable solely by virtue of their status; responsibility is refocused on those who actually exercise management control. Liability may be individual or joint and cannot be waived unless a formal objection is recorded in the relevant meeting minutes.
- Virtual corporate governance by default: Board and shareholder meetings may now be held electronically by default, so long as participants’ identities are verified, meetings are properly recorded and all shareholders can fully participate. Virtual meetings and electronic voting no longer require express authorisation in the constitutional documents, easing logistics for cross‑border investors and supporting Bahrain’s wider digital‑transformation agenda.
- Single-shareholder closed joint stock companies: A closed joint stock company (BSC Closed) may now be established by a single shareholder, who can exercise the powers of both the founding and general assemblies, subject to conditions to be set by the Ministry of Industry and Commerce. This relaxes the former minimum-two-shareholder rule and gives investors more flexibility when designing holding, JV and platform structures.
- Continuation of companies post-partner exit: Where a company’s constitutional documents are silent on continuation following the withdrawal, death or legal disqualification of a partner, the period for remaining partners to unanimously agree on continuation has been extended from 15 working days to 90 working days. This provides materially more time for complex situations, particularly in family-owned and professional partnerships.
- Abolition of unincorporated joint ventures (Musharakah).: All references to “partnerships by participation” have been deleted from the CCL and the chapter regulating them has been repealed. Existing arrangements were required to regularise their status within three months of the law’s effective date
- Enhanced regulatory oversight. The powers of the Ministry of Industry and Commerce to inspect and require copies of all books, documents and records may now be directed to shadow managers in addition to directors, managers, employees and auditors.
Taken together, these reforms give boards a sharper, liability-aware and digitally enabled corporate toolkit. From a governance perspective, the expanded liability regime means that D&O insurance, delegation matrices and board processes should be reviewed as part of any restructuring or new investment. The changes reflect a continued shift toward greater regulatory rigour in transparency and corporate governance, even as foreign investment entry barriers are lowered.
3. Liberal FDI Regime
Bahrain sits at the more liberal end of the GCC’s FDI spectrum. Key recent steps include Decision No. 53 of 2024 (effective 17 October 2024) and Decision No. 71 of 2025 (effective 27 November 2025), both amending Decision No. 40 of 2021 specifying the commercial activities that foreign companies may be licensed to practise in Bahrain.
Foreign investors can generally hold up to 100% of the share capital in many core sectors—including manufacturing, most professional services, sale and trade, logistics, ICT and a wide range of professional activities—subject to licensing and strategic‑sector carve‑outs.
In October 2024, Bahrain further relaxed foreign-ownership conditions, enabling qualifying foreign companies to sell certain goods without a local partner and to fully own their business where they operate in at least ten countries or generate annual revenues above EUR 750 million. The minimum capital requirement for foreign-owned companies was also reduced from BHD 2 million to BHD 100,000.
Five activities, including electric power generation, electric power transmission and distribution, management and operation of ports and private jetties, and real estate brokerage, were also opened for 100% foreign ownership on an unconditional basis.
There are no restrictions on the repatriation of capital, profits or dividends, other than for income derived from activities in the oil and gas sector.
For corporate investors, foreign-ownership caps are rarely the main constraint. The decisive questions are tax treatment, regulatory requirements, capital-raising options and operational fit.
4. Regulation-Led Financial Centre: CBB, Fintech and Open Banking
The financial sector remains at the core of Bahrain’s value proposition, with services expected to drive much of the Kingdom’s growth through 2025–2026. The Central Bank of Bahrain (CBB) acts as a single, integrated supervisor across conventional and Islamic banking, insurance, capital markets and investment business under detailed modular rulebooks.
Bahrain was the first MENA jurisdiction to roll out a full open-banking regime, with final regulations issued in 2018, mandatory bank compliance from 2019 and the Bahrain Open Banking Framework launched in 2020. The ecosystem has since scaled rapidly: the Kingdom now hosts well over a hundred fintech and digital-finance providers, supported by the CBB’s regulatory sandbox, FinHub 973 and the region’s first central-bank-regulated open-finance platform.
For corporates, this makes Bahrain a compelling regional financial and digital‑finance hub—a market where traditional banking, Islamic finance and fintech sit under a single, internationally benchmarked regulatory umbrella. The consolidated oversight model helps compress approval timelines from pilot to production, offering a practical edge over more fragmented licensing environments in the wider region.
5. Energy, Infrastructure and Sector Trends
Bahrain is not positioning itself as a mega‑producer, but it remains closely tied into the Gulf’s oil, gas and downstream value chain. The USD 7 billion expansion of the Sitra oil refinery targets a roughly 50% increase in crude-processing capacity from 267,000 b/d to about 400,000 b/d, supporting manufacturing growth and refined‑fuel exports. On the infrastructure side, Bahrain is expanding and upgrading ports, logistics parks and industrial zones to reinforce its role as a distribution and light-manufacturing hub feeding into Saudi Arabia and the wider GCC.
Across 2024–2026, several sectors continue to trend strongly. Financial services and fintech remain the largest non-oil contributor to GDP and a primary destination for regional and international capital. Industrial and logistics investment led new FDI in 2024, with manufacturing and logistics assets serving as a base for Saudi Arabia and the wider GCC. ICT and digital‑economy projects are supported by pro-cloud policies and demand from financial and government sectors. Tourism and hospitality are benefitting from infrastructure upgrades and proximity to Saudi business and leisure travel, with overnight visitors reported to have risen by around 8–9% year-on-year in early 2025‑.
6. Tax
Bahrain’s tax framework is gradually aligning with regional and international standards. VAT, introduced as part of the GCC VAT framework, now stands at 10%. Alongside company law reform, Bahrain is also introducing a broader corporate income tax (CIT) regime. Previously, corporate income tax applied only to companies operating in the oil, gas and hydrocarbon sector. As of 1 January 2025, Bahrain implemented the OECD’s BEPS Pillar Two rules by introducing the Domestic Minimum Top-up Tax Law, imposing up to a 15% Domestic Minimum Top-Up Tax (DMTT) on large multinational enterprises within the scope of Pillar Two. A comprehensive CIT law is expected to follow, applying to companies not falling within the scope of Pillar Two. The draft CIT law has not yet been published but is expected to be introduced over the course of 2027.
Based on the Bahraini Cabinet’s announcement, a 10% CIT is expected to apply to businesses meeting either of the following thresholds:
- Annual revenues exceeding BHD 1 million, or
- Net annual profits exceeding BHD 200,000.
It is anticipated that the CIT would apply only to the portion of profits exceeding the BHD 200,000 threshold.
The draft CIT law is expected to set out the main framework, with detailed implementation rules and administrative procedures in accompanying regulations. While the final text and implementing regulations are not yet publicly available, boards should already factor CIT into medium-term structuring, profit-allocation and substance planning for Bahraini entities.
Businesses operating in or through Bahrain should proactively review their tax position as the framework evolves. The transition to a broader tax regime will raise structuring, substance and profit-allocation questions, and early planning can help manage exposure and ensure positions remain defensible as implementation approaches.
7. Data and Regional Convergence
On the operational side, Bahrain’s Personal Data Protection Law (PDPL) and sectoral rules shape how corporates use cloud and cross-border data solutions. Cross-border transfers of personal data must comply with PDPL rules on “adequate” jurisdictions, consent or other legal bases, and regulated entities—especially financial institutions—are subject to additional cloud-outsourcing controls.
As Bahrain progressively converges with regional peers on tax architecture, multinationals can design consistent tax and compliance frameworks across Bahrain, the UAE and Saudi Arabia, while still benefiting from a cost-competitive, business-friendly platform that stands comparison with leading mid-sized hubs globally.
8. How Corporates Are Using Bahrain in 2024–2026
In practice, investors are using Bahrain in several distinct ways: as a regional financial hub and booking centre, hosting banks, insurers, asset managers and treasury vehicles under CBB oversight; as a fintech and digital-finance platform, enabling companies to pilot and scale products under its sandbox and open-banking regime before rolling them out across neighbouring markets; as an industrial and logistics base, deploying capital into industrial parks and logistics zones serving both Bahrain and Saudi Arabia; and as a shared-services and centres-of-excellence location, consolidating back-office, IT, compliance and customer-support functions to take advantage of Bahrain’s skilled bilingual workforce and competitive cost profile.
9. Key Boardroom Questions — Bahrain Lens (2025–2026)
Corporate boards assessing their Bahrain exposure should consider the following:
- Do existing Bahraini vehicles — whether WLL, BSC Closed, BSC Public or branches — reflect the latest CCL reforms, including single-shareholder closed JSC options and the abolition of partnerships by participation, or are legacy structures still in place?
- Are foreign-ownership opportunities being fully leveraged in sectors where operational control is critical, given that 100% foreign ownership is available in manufacturing, logistics, ICT and professional services?
- In light of strong FDI inflows since 2023 and continued net inflows through 2024–2026, is the company under- or over-weighted on Bahrain relative to its demonstrated capacity to absorb and retain capital?
- Could certain functions — treasury, regulated finance, back-office or logistics — be more efficiently based in Bahrain given its cost base, financial-sector maturity, open-banking infrastructure and connectivity to Saudi Arabia?
- Do Bahraini contracts, shareholder agreements and governance documents reflect expanded director and shadow-manager liability, virtual-meeting defaults and updated dispute-resolution options, or do they need to be refreshed?
- In the context of heightened geopolitical tensions and regional conflict risk, how resilient is the group’s Bahrain footprint in terms of supply‑chain continuity, data‑hosting, sanctions exposure and business‑continuity planning?
- Does the balance between Bahrain and other GCC hubs still reflect the board’s risk appetite for concentration, market‑access and geopolitical diversification, or is a rebalancing of regional exposure warranted?
With a proposed 10% CIT on the horizon for 2027, boards should also model the impact on existing and planned Bahraini entities, review contracts for change-in-law clauses, examine opportunities for entity rationalisation, ensure inter-company arrangements comply with the arm’s length principle and identify any permanent establishment risks before the new tax regime takes effect.
How Al Tamimi & Company Can Help
Al Tamimi & Company is uniquely positioned to advise on the full range of corporate, regulatory and transactional matters arising from Bahrain’s evolving investment landscape. Whether you are establishing a new presence in Bahrain, restructuring existing vehicles in light of the CCL amendments, navigating CBB licensing and fintech regulation, or assessing the implications of the proposed corporate income tax, our team is ready to assist.
Written by